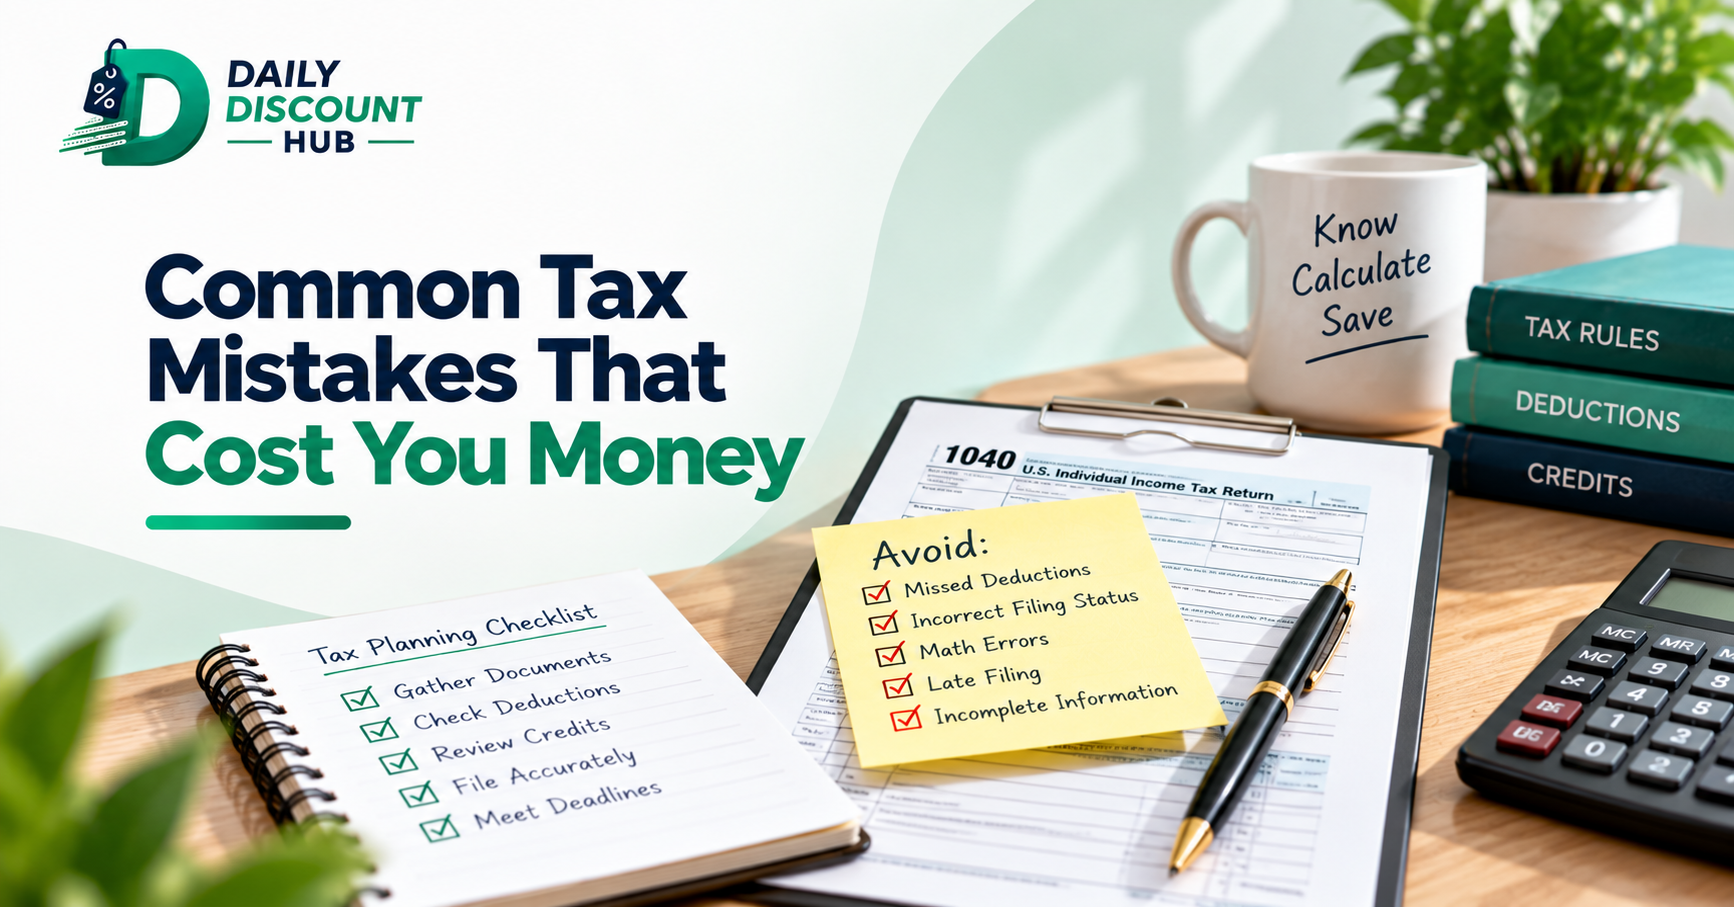
Every year, taxpayers lose thousands to preventable tax mistakes - missed deductions, misunderstood tax regimes, miscalculated income, and filing errors made under deadline pressure. Most of these mistakes aren't dramatic. They're quiet: a deduction you didn't know you qualified for, a tax bracket you misjudged, a credit you forgot to claim. Individually small, but they add up year after year. The good news is that nearly all of them are preventable with one habit: checking your numbers with a tax calculator before you're staring down a filing deadline.
Calculate GST, VAT, or sales tax on a purchase and see the tax amount and total price you'll actually need to pay.
The cost of a tax mistake rarely shows up as a single number. It's the deduction you forgot to claim last year and the year before that. It's the estimated payment you underpaid, now sitting there accumulating a penalty. It's the time spent scrambling to amend a return because something was rushed at the last minute. None of these costs are obvious in the moment, which is exactly why they're so easy to repeat.
A tax calculator doesn't fix this by being smarter than you - it fixes it by giving you a number to react to before the deadline, instead of after. Once you can see an estimate of what you owe or what you're overpaying, mistakes that were invisible suddenly become obvious.
Below are eight mistakes that show up repeatedly, regardless of income level or filing complexity. Each one is preventable, and each one is exactly the kind of error a tax calculator is built to catch.
Many tax systems now offer more than one way to calculate your liability—often an older structure with more deductions and a newer, simplified structure with lower rates but fewer deductions available. Choosing between them isn't always obvious, and a lot of taxpayers default to whichever option was used last year without checking if it's still the better fit.
Real example: A taxpayer with several eligible deductions stays on a simplified regime out of habit, overpaying by a meaningful margin simply because they never compared both options side by side.
A tax calculator solves this by letting you plug your numbers into both regimes and instantly compare the result. Instead of guessing which one is better, you see the actual number for each.
Michael focuses on budgeting techniques, financial planning basics, expense management, and consumer financial education. His content is designed to help readers make informed financial decisions.
This is the single most common – and most expensive – mistake on this list, because it’s invisible. You don’t get a notification telling you “you missed a deduction.” You simply pay more than you needed to, and you may never find out.
Commonly missed deductions include:
A tax calculator that walks through deduction categories prompts you to check each one, rather than relying on memory under deadline pressure.
Income reporting errors usually aren’t intentional – they’re a result of forgotten income sources. Freelance income from a single small project, interest earned on a savings account, or a side gig that didn’t feel “official enough” to report can all slip through the cracks.
Overreporting happens too, usually when the same income gets counted twice across different statements or platforms. Both directions cost you: underreporting risks penalties, and overreporting means paying tax you didn’t actually owe.
Running your total income through a calculator forces you to itemize each source individually, which makes duplicate or missing entries much easier to spot than when everything is lumped into one rough estimate.
Side income brings its own tax responsibilities, and a lot of people don't realize how much it changes their overall calculation until it's too late to plan for it. A consistent side hustle isn't just extra income - it can push you into a different tax bracket, create new reporting requirements, and introduce categories of deductible expenses you weren't tracking before.
Common gaps include:
This is less a single mistake than a habit that causes most of the others. Tax season pressure pushes people to rush - skipping deductions, misreporting income, and making entry errors simply because there's no time left to check the work carefully.
Credits and deductions are often confused, but they work very differently - a deduction reduces your taxable income, while a credit reduces your tax bill directly, which usually makes it more valuable. Despite that, credits are commonly overlooked because they're less talked about and easier to miss if you're not specifically looking for them.
A calculator that separates credits from deductions in its breakdown makes this distinction visible, instead of burying both under one vague "tax savings" category.
Even careful taxpayers make basic arithmetic mistakes when working through tax brackets, deductions, and credits by hand or in a spreadsheet without built-in validation. A single misplaced decimal or skipped line item can throw off an entire estimate.
This is one of the most straightforward problems a calculator solves: the math itself is no longer something you have to get right under pressure.
Even a perfectly calculated return loses value if it's filed late or missing required documentation. Common gaps include missing quarterly payment deadlines for freelance or business income, forgetting to retain receipts for claimed deductions, and incorrect withholding assumptions carried over from a previous year.
The value of a tax calculator isn’t that it replaces careful judgment – it’s that it gives your judgment something concrete to work with. Instead of estimating your tax situation from memory, you get an accurate number to react to, adjust, and re-check as your income or expenses change throughout the year. For a broader explanation of consumption taxes and how they are calculated, see our GST/VAT calculation guide.
Tax planning works best when it is part of your broader financial routine rather than a once-a-year task. For practical guidance on managing spending, planning ahead, and making better financial decisions throughout the year, explore our budgeting and finance guides.
Small business owners and freelancers face a wider set of tax mistakes than salaried taxpayers, mostly because their tax situation has more moving parts. The most frequent issues include:
Freelancers face a related but slightly different set of issues, since income often arrives irregularly and from multiple clients or platforms at once:
Tax calculation tools have moved well past simple arithmetic. Modern calculators can model multiple tax regimes side by side, forecast quarterly obligations for freelance income, and flag commonly missed deduction categories automatically. They can also help users identify legitimate deductions and planning opportunities when considering how to reduce tax liability without relying on guesswork.
That shift matters because it moves tax planning from a once-a-year scramble into something you can check in on throughout the year - closer to ongoing financial planning than a single annual event.


Enter any original price and a discount percentage to instantly see your final price, exact savings, and whether the deal is genuinely worth it.
Don't just see the % off — get a deal score from 1–10 and a clear verdict: Worth It, Average, or Bad Deal. Stop getting fooled by inflated "original" prices.
Before submitting your return, take a final pass through your income, deductions, credits, and estimated tax liability. You can avoid these mistakes with our Tax Calculator by checking your figures before filing and identifying calculation errors that may otherwise go unnoticed under deadline pressure.
The most consistently costly mistakes are: missing eligible deductions (80C, 80D, home loan interest), selecting the wrong tax regime without comparing both options, not reporting income from all sources (interest, capital gains, freelance earnings), filing at the last minute under pressure, and relying on manual calculations that contain arithmetic or formula errors. Each of these is preventable with basic planning and a reliable tax calculator.
In a progressive tax system, there’s no single “bracket” that applies to all your income – different portions are taxed at different rates. The mistake most people make isn’t choosing the wrong rate but choosing the wrong regime – old vs. new – without comparing which one produces a lower liability given their specific deduction profile. This comparison is the most valuable thing a tax calculator does in under 60 seconds.
Deductions reduce your taxable income before tax is calculated. Credits reduce your tax payable directly after tax is calculated. The practical difference is significant: a ₹50,000 deduction at a 20% slab reduces your tax by ₹10,000; a ₹50,000 credit reduces your tax by ₹50,000. Credits are considerably more valuable – the Section 87A rebate, for example, eliminates all tax payable for eligible taxpayers.
Investment certificates and receipts (80C instruments, insurance premiums, NPS statements), home loan interest certificates, rent receipts and HRA documentation, Form 16 and Form 16A from all TDS deductors, bank statements showing interest income, capital gains statements from mutual fund platforms and brokerages, business expense receipts and invoices if self-employed, and charitable donation receipts with 80G certification.
Selected For You
Join our free newsletter and receive smart deals, savings hacks, and new tools every week.
Free smart tools and trusted guides to help you save money on every purchase, every day.
Company
Explore Guides
Quick Links
© 2026 Daily Discount Hub. All rights reserved.